One of the main reasons people buy off-plan in Dubai is that they don't need the full price on day one. Developers spread payments over the construction period — and sometimes for years after you get the keys. But a "60/40" or "1% a month" headline can hide very different cash-flow commitments, so it pays to understand exactly how a plan works before you sign.
This guide explains the main types of off-plan payment plan in Dubai, what you pay upfront, how your money is protected, and how resale and mortgages fit in.
What Is an Off-Plan Payment Plan?
An off-plan payment plan is the schedule, set by the developer and written into your Sale and Purchase Agreement (SPA), for paying for a property that is still being built. Instead of paying the full price at once, you pay a booking amount, then instalments tied to dates or construction milestones, and the balance on or after handover.
Plans are usually described as two numbers — the share paid before handover and the share paid on or after handover. A 60/40 plan means 60% during construction and 40% at completion.
Construction-Linked Plans: 50/50, 60/40, 70/30
This is the most common structure in Dubai. You pay a deposit on booking, then instalments during construction, and the remaining balance when the building is completed and handed over.
Typical splits, with examples from projects we currently list:
| Plan | During construction | On handover | Example |
|---|---|---|---|
| 75/25 | 75% | 25% | Expo Valley Views – Ghadeer, Elaris Rise |
| 70/30 | 70% | 30% | Binghatti Skyflame |
| 65/35 | 65% | 35% | The Wilds Residences |
| 60/40 | 60% | 40% | Aurelia Residence, The Tranquil at Sobha Central, Rise by Athlon |
The construction share is usually split into a booking deposit (often 10–20%) followed by instalments — either on fixed dates or when the project reaches set construction milestones.
Who it suits: buyers who will have the handover balance ready in cash, or who plan to take a mortgage at completion. The larger the handover payment, the more important it is to plan how you will fund it.
Post-Handover Payment Plans
With a post-handover plan, part of the price is paid after you receive the keys — typically 30–50% of the price, spread over one to five years, and in some cases longer. A common format is a fixed percentage each month, for example 1% a month after completion.
This arrangement is with the developer, not a bank, so there is usually no interest charged and no mortgage application. That is why it appeals to investors: once the property is let, the rent can cover part of each instalment.
The trade-offs:
- Price premium. Projects with long post-handover plans can be priced higher than comparable units sold on shorter plans. Compare the price per sq ft with similar buildings, not just the monthly amount.
- A long commitment. You are paying the developer for years after handover, alongside service charges and any vacancy between tenants.
- Refinancing is not automatic. If you plan to switch to a bank mortgage later, banks may require the developer balance to be settled first. Check this before relying on it.
- Missed payments are serious. The SPA sets out penalties for late payment, which can be significant.
What You Pay Upfront
The booking deposit is not the only cost on day one. When you buy off-plan you should also budget for:
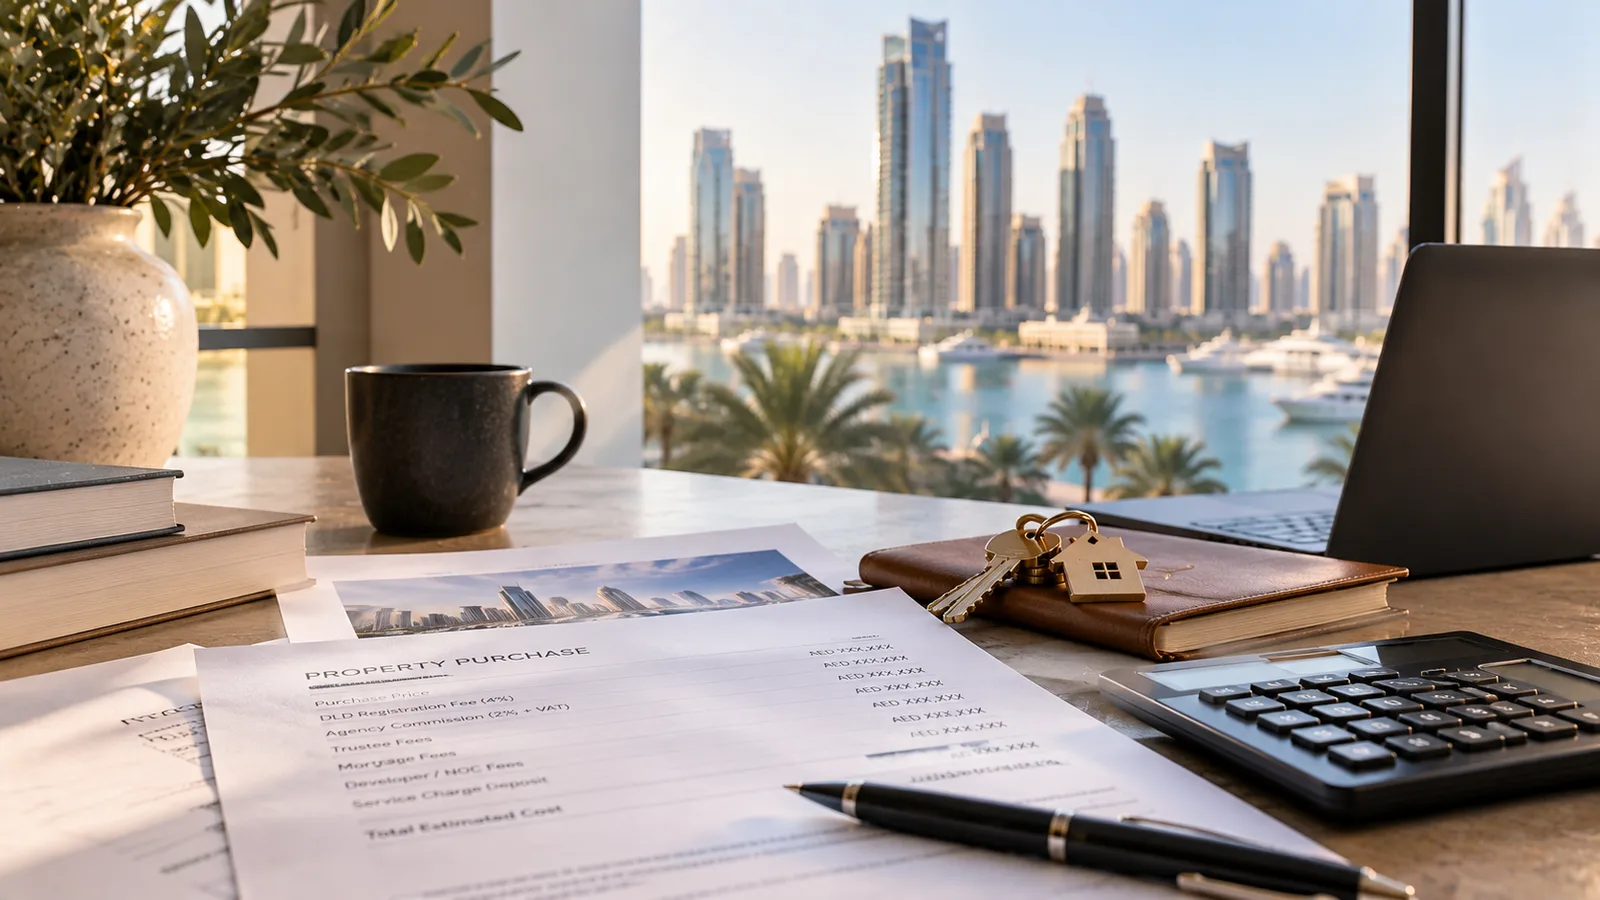
- Dubai Land Department (DLD) fee — 4% of the purchase price, usually paid at booking when the unit is registered.
- Oqood registration — the DLD's interim register for off-plan units, with a small administrative fee.
- Agency fee — on new launches this is often paid by the developer, but confirm it in writing.
So on a AED 1,000,000 apartment with a 10% booking deposit, you would typically need around AED 140,000 upfront — the AED 100,000 deposit plus around AED 40,000 in DLD fees. See our full breakdown of what it costs to buy property in Dubai.
How Your Payments Are Protected
Dubai has two main protections for off-plan buyers:
- 1. Escrow accounts. Under Dubai Law No. 8 of 2007, payments for an off-plan unit must go into an escrow account for that specific project at a DLD-approved bank. The developer can only draw money as construction progresses, with sign-off from the project consultant and the authorities.
- 2. Oqood registration. Your purchase is recorded on the DLD's interim register (Oqood) until the title deed is issued at handover. This is your official record of the purchase.
Escrow protects the money in the account; it does not guarantee a handover date or that prices will rise. Always pay into the project's escrow account — never to a personal account or an unregistered intermediary — and check the project and your Oqood record on the Dubai REST app or the DLD website. For more on choosing a developer, see how to judge a newer Dubai developer before buying off-plan.
Selling Before Handover
Many investors plan to sell before completion. That is possible, but developers usually only issue the No Objection Certificate (NOC) needed for a resale once a minimum share of the price has been paid — commonly around 30–40%, and higher on some projects. The exact threshold is in your SPA.
A resale before handover also carries costs: the buyer pays the 4% DLD fee on the new price, and many developers charge an NOC or transfer fee. Factor these in if you are counting on an early exit.
Can You Use a Mortgage?
Most buyers on a construction-linked plan pay the instalments in cash and take a mortgage, if needed, at handover — when the property becomes a ready home that banks lend on more readily. A few UAE banks now offer financing during construction, but it is typically limited to a portion of the value and to approved projects and developers.
If you will need a mortgage for the handover payment, speak to a bank or mortgage adviser early, ideally before you book. Our guide to mortgages in Dubai for expats explains deposits and eligibility.
How to Choose the Right Plan
- Work out your total cash need, not just the booking deposit — include DLD fees and every instalment date.
- Plan the handover payment — cash, mortgage or post-handover instalments — before you commit.
- Compare price per sq ft, not just the payment plan. A generous plan can come with a higher price.
- Check whether instalments are date-based or milestone-based. Milestone plans move with construction; date-based plans do not.
- Read the SPA for late-payment penalties, resale thresholds and what happens if the handover is delayed.
- Check the developer's delivery record on previous projects.
For the bigger picture, read our off-plan buyer's guide and our comparison of off-plan vs ready property.
Find a Plan That Fits Your Budget
Every project we list shows its payment plan and expected handover date. Browse our off-plan projects, or contact EasyAcres and we will compare plans side by side — including the full cash you need at each stage.
Payment plans, fees and bank rules change and vary by developer and project. This guide is general information, not financial or legal advice — always confirm the terms in your SPA and check current fees with the Dubai Land Department.